What means monetizing ?
When I read some documentation on various websites it is sometimes hard to understand the definitions and explanations around “monetizing”. that’s why I want to explain this very important topic with the help of a daily example that everybody will understand.
Suppose you own a house. And the market value of that house should be 300.000 USD.
You have no outstanding credits at all. Even the car you drive is cash paid. And on your bank account you have 50.000 USD in cash. And there are no debts at all as well.
So: you have available: 300.000 in assets and 50.000 in cash funds.
Now you want to start up a business and therefore you need 250.000 USD. But you only have 50.000 USD in cash.
We have 2 options:
Option 1: you sell your house and try to get 300.000 USD for it. Together with the 50.000 you already have you have enough to start your business. But you have no longer that house. So you will have to rent one. Hmm… Does not seem to be a smart option.
Option 2: you ask a bank to give you a credit line “against your house” that you put as collateral.
You negotiate with the bank and the bank will send someone to make an appraisal for your house. AND DO KNOW THAT THE BANK WILL ISSUE A COST FOR THIS APPRAISAL! This appraisal report shows a value of 300.000 USD. This is the TOTAL value of your house. We can say that 300.000 is the “FACE VALUE” of your house. Will the bank give you 300.000 in credit for this house? I don’t think so. The bank will give you maybe 60%, maybe 70% or might even be 80% credit. But it all depends on the “value points” of that house. Meaning, how old is the house, the location, building construction, isolation, etc. So many criteria will be taken in consideration to give you a “credit line”. This we call the “LOAN TO VALUE” of your asset. What we also know is that the bank will ask a “fee” (bank commission) to open this credit line.
Exactly the same is happening with financial instruments (FI). Depending on which bank issued the FI, underlying funds (guarantee) maturity, etc, the bank will also give you an “appraisal” (LTV) for the FI. This can vary from 70% till 90% for TOP WORLD BANKS. Now you will understand that a FI issued by a local bank behind the corner of a small city somewhere in a small country, will not receive a high appraisal. Sometimes it will even not be possible to get this FI monetized !
What we actually did is monetize our house (asset) to get cash money. But DO NOT FORGET: THE CREDIT MUST BE PAID BACK WITH INTERESTS! over a time period, the bank determined. This time period can be 10 till 25 years in our example. This is called the “Maturity” (time of the loan). For FI the time periods for a credit line is mostly 1 year and 1 day. HOWEVER: Some monetizers work with NON RECOURSE LTV. In that case, the client DOES NOT HAVE to pay back the “CREDIT”. But the LTV will be much lower. Ask us for more details regarding this topic.
What do we have to remember with this story:
We can monetize “an asset” by a bank (or even another institution) with a credit line.
The bank asks for a cost for the “appraisal” and opening of the credit line. => So for monetizing a financial instrument, there are fees that NEEDS to be paid. Depending on the Face Value, type of instrument, BANKS ALWAYS ASK FEES!
What CAN BE monetized ?
In fact, everything with a value can be monetized! But it all depends again on WHAT do you want to get monetized. As long as you can find someone (a bank or institution) that is prepared to give you money (credit line) against “your asset”. So some “assets” have high LTV, and some have low LTV. And depending on the origin of your asset, different procedures must be followed.
The stronger the “ASSET”, the higher the LTV.
Many people, brokers, intermediates contact us to monetize “an asset”. They have prepared all documents on procedures, how it needs to be done, what will be the LTV and profit they will get etc. These end up directly into the trash bin.
We, in MSfinadvice, will never give you an appraisal! Based on our experience and relations, we will contact the right “Monetizer” for your asset. And it will be that Monetizer that will set up the rules. Not the owner of the asset or his intermediates. And if owners of hundreds of millions of assets are not prepared to pay fees to banks, Monetizer or lawyers, they can put their assets in the fridge and keep it there for a long time. We in MSfinadvice never ask UP FRONT FEES. We only work based on success fees! NO CURE, NO PAY !
Some examples of assets that can be monetized: Gold, Silver, Gemstones, Most Financial Instruments, etc.
These Are The Top Reasons Why People Fail in Bank Financial Instruments Transactions:
One of the partners I work with for issuing and monetizing of FI, send me a couple of reasons why many of these “transactions” FAIL. Might be interesting to read !
1. Price Shoppers – People are lured in by fake artificially low prices of financial instruments offered by scammers. When a scammer isn’t delivering anything real, they can afford to offer you the deal of the century! Price Shopping clients will always get a bargain that will cost them a fortune.
2. Intermediates thinking they can pretend to act as owner/buyer and want all the docs, contracts done by them. They have no intention what they are doing but feel themselves important enough to act like they own everything. “Nobody can do anything without them? Right? – WRONG. They just screw up the deal with their EGO. They have a professional google /Yahoo /protonmail /hotmail… hmm.. Website? No need. Even a registered company or business registration is NOT NEEDED. But they are the “MAN”. Even they want the biggest piece of the cake, because they feel the most important. They are going to make the rules. They are telling everybody who gets how many commissions. They have some contacts and think that now they are the BOSS. We never saw a deal happening with this kind of people.
3. Greed Freaks – People get blinded by Greed and the possibility of becoming an Instant Millionaire, so they stop thinking Rationally and Clearly. They stop being careful and start being careless which causes them to not see all the obvious warning signs that lead right to a scammer’s front door. Greed and Ignorance will make you lose your sense of reasoning. Many people don’t want to hear these things because truth hurts, but we will keep saying the truth regardless.
4. Speed Dating – People that have never closed a real transaction before create a complex set of financial instrument procedures and then engage dozens of brokers to trawl the internet as a speed dating service trying to find another party to match their procedure. This is the playbook of an amateur who has as much chance of winning the lottery as he does change the whole financial instruments industry to solely work with his isolated ill-conceived procedures such as PROVIDER MOVES FIRST, SEND SWIFTS FIRST BEFORE WE PAY ANY FEES ETC. These are joker broker nonsense, no bank or provider will engage you in your own procedure because in the financial industry, the funds’ owner makes the decision. You cannot walk into a bank and tell them to give you a loan under your own terms, it is IMPOSSIBLE.
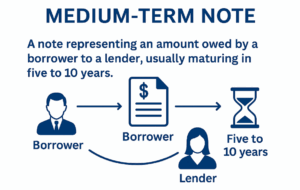
5. Free – Many people are under the false illusion that they can close a loan, BG, SBLC or MTN transaction free of charge without spending any money upfront. They want the Funder or bank instrument provider to pay the upfront fees so that they can complete the financial transaction for FREE, taking no risk and investing none of their own money. Those types of free deals do not exist in the real world, if they did, there wouldn’t be any poor man in the world today. Banks have NEVER issued multimillion dollar assets to customers for FREE and then hope the customer pays them later. This would be financial lunacy! You don’t believe? Please GO and contact YOUR banker and ask these questions. Please don’t believe in fairy tales.
6. Unrated Bank Trap – Most Unrated Bank Instruments are cheap because they aren’t worth the paper they are written on! Anyone can buy a banking license from an offshore country for $2,000 USD and call themselves a bank. There is a reason Unrated Banks charge $25,000 USD for a 100 Million Financial Instrument! They know it’s not worth $25,000! You can’t buy crap and get rich, you have to buy quality financial instruments from Rated Banks.